Dodl Review: AJ Bell's 0.15% App, £1 Minimum, 95 Picks
Dodl charges 0.15% a year with a £1 monthly minimum and no dealing fees. What it costs from £2k to £100k, the 95 investments, LISA and pension rules.
This Dodl review starts with the one number AJ Bell built the app around: a 0.15% yearly account charge, taken monthly, with a minimum of £1 a month for each account you hold. There is no fee to buy or sell, no subscription and no charge to open, transfer in, withdraw or close. In return you get a short menu of about 95 investments instead of the thousands on AJ Bell’s main platform, and you manage everything through the app.
Every charge and rule below comes from Dodl’s own pages, checked on 15 November 2026.
Dodl at a glance
| What you pay or get | |
|---|---|
| Account charge | 0.15% a year of your investments, per account, minimum £1 a month |
| Dealing charge | None |
| US shares | FX charge of 0.75% on the first £10,000 of a trade, 0.50% on the next £10,000, 0.25% above £20,000 |
| Foreign dividends | 0.50% FX charge to convert them to pounds |
| UK shares | 0.50% stamp duty on purchases, plus the £1.50 PTM levy on trades over £10,000 (government charges, not Dodl’s) |
| Interest on uninvested cash | 3.80% AER variable in the investment ISA and Lifetime ISA; none in the pension or general investment account |
| Accounts | Investment ISA, Lifetime ISA, pension, general investment account |
| Not offered | Junior ISA, joint accounts, business accounts, advice |
| Minimums | £25 a month by regular investment; £100 as a lump sum |
| Investments | 7 ready-made AJ Bell funds, a pension builder fund, 29 themed funds and ETFs, 58 UK and US shares |
What Dodl actually costs
The 0.15% is worked out on the value of your investments in each account and collected monthly from the cash in that account. Dodl warns you before it takes the charge, but you need to leave some cash uninvested to cover it.
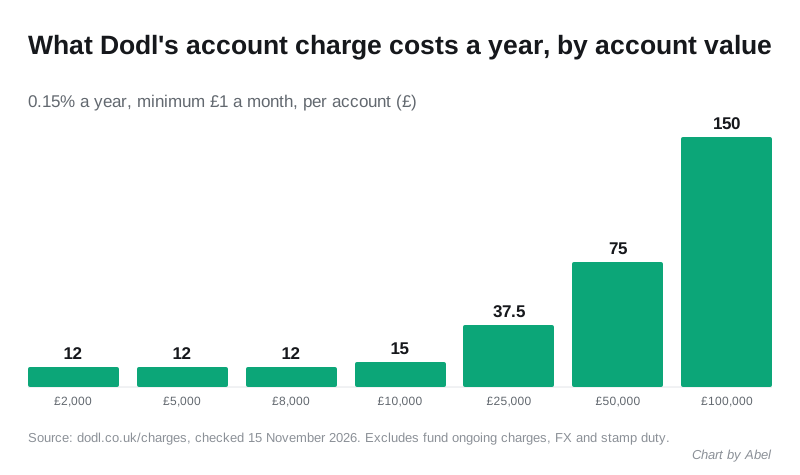
The £1 monthly minimum matters more than the headline rate on a small pot. £12 a year divided by 0.15% is £8,000, so below about £8,000 in an account you pay the flat £12 and the effective rate is higher than 0.15%. On £2,000 that £12 is 0.60% a year. On £5,000 it is 0.24%. Above £8,000 the percentage takes over: £15 a year on £10,000, £75 on £50,000 and £150 on £100,000.
The minimum applies to each account separately. Someone with an investment ISA and a Lifetime ISA at Dodl, each holding £3,000, pays £1 a month on both, so £24 a year in total.
The account charge also has no cap, which is where Dodl stops being the cheap option for large share and ETF portfolios. At £100,000 Dodl charges £150 a year. Hargreaves Lansdown caps its charge on shares and ETFs at £150 a year from about £42,900 upwards, so above £100,000 of ETFs, HL’s capped fee becomes cheaper than Dodl’s, as our Hargreaves Lansdown review shows. Below that level, and for any amount held in funds, Dodl’s 0.15% is lower.
The charges on top of the 0.15%
The account charge is not the full cost. Each fund and ETF has its own ongoing charge, taken inside the fund by the manager. The AJ Bell Balanced fund, one of Dodl’s ready-made options, lists an ongoing charge of 0.31% a year on its factsheet dated 30 September 2026, plus 0.05% transaction costs. So £10,000 in that fund costs roughly £15 in Dodl’s account charge and about £31 in fund charges, before transaction costs.
Shares carry their own costs. Buying UK shares attracts 0.50% stamp duty, and any trade over £10,000 pays the £1.50 PTM levy; our page on stamp duty on shares in UK apps explains both. Buying or selling US shares such as Apple or NVIDIA costs a tiered FX charge, and any dividends paid in dollars cost 0.50% to convert. Dodl’s own example: a £15,000 US share purchase pays 0.75% on £10,000 and 0.50% on £5,000, which is £100.
A note on Dodl’s comparison table. Its charges page shows Dodl at 0.00% and £0 a year for a £10,000 ISA. That figure carries an asterisk: it is a 12-month fee-free offer for people who deposited at least £1,000 into a Dodl ISA between 1 February and 30 April 2026. If you open an account now, you pay the standard 0.15%.
What you can invest in
Dodl’s range is deliberately short. On 15 November 2026 it listed:
- Seven ready-made AJ Bell funds: cautious, moderately cautious, balanced, moderately adventurous, adventurous, global growth and responsible screened growth. Each is a complete portfolio in one fund.
- A pension builder fund, the default ready-made option for the Dodl pension.
- 29 themed investments, mostly index funds and ETFs: the Vanguard FTSE 250 ETF, SPDR S&P 500 ETF, HSBC FTSE All-World index fund, iShares Core MSCI Emerging Markets ETF, two Vanguard LifeStrategy funds, bond funds including the iShares Core UK Gilt ETF, the iShares Physical Gold ETC and a BlackRock sterling money market fund.
- 58 shares, split between UK names (Tesco, Greggs, BP, Lloyds, Rolls-Royce, National Grid) and US names (Apple, Microsoft, Amazon, NVIDIA, Tesla).
For most long-term investors that is enough: a global tracker or a single ready-made fund covers the basics. It is not enough if you want individual investment trusts, a particular active fund, or a share outside the list of 58. For those you need AJ Bell’s main platform or a wider app; our best stocks and shares ISA apps comparison lists the alternatives.
The Dodl Lifetime ISA
Dodl’s Lifetime ISA is one of the cheapest ways to hold an invested LISA over many years, and it is the account where the 0.15% charge suits the product best. The rules are the government’s, not Dodl’s:
- You must be 18 to 39 to open one, and can pay in until you are 50.
- You can pay in up to £4,000 a tax year, and the government adds a 25% bonus, up to £1,000 a year. That £4,000 counts towards your £20,000 overall ISA allowance.
- You can withdraw without a charge to buy your first home (up to £450,000, with the account open at least 12 months) or from age 60.
- Any other withdrawal pays a 25% charge, which takes back more than the bonus.
Two changes from the Budget on 28 October 2026 matter here. From 29 October 2026, a first-time buyer whose home costs more than £450,000 pays a 20% withdrawal charge instead of 25%, so they no longer lose part of their own money. And the government plans a new First Time Buyer ISA from April 2029 that will replace the Lifetime ISA for new savers. Existing Lifetime ISAs, including Dodl’s, carry on under the current rules. The government’s policy paper on the withdrawal charge sets out the first change.
Uninvested cash in the Dodl Lifetime ISA earns 3.80% AER variable. Our best Lifetime ISA apps guide compares Dodl with cash LISAs from Moneybox, Plum and Tembo, and the Lifetime ISA calculator shows what the bonus adds up to.
The Dodl pension
The pension is a simple personal pension with the same 0.15% charge. You get 25% basic-rate tax relief added to what you pay in, higher-rate taxpayers claim the rest through self-assessment, and you can pay in up to your earnings, within the £60,000 annual allowance. You can take money out from 55, rising to 57 in 2028.
Dodl pays no interest on cash in the pension, so money left uninvested earns nothing. Transfers in are free. Our best SIPP apps page compares Dodl’s pension with Freetrade, InvestEngine, Vanguard and PensionBee on pots of £20,000, £50,000 and £150,000.
The 3.80% on cash
Dodl pays 3.80% AER variable on uninvested cash in the investment ISA and Lifetime ISA. That is higher than many investing apps pay and, inside an ISA, it is tax-free. Remember the cash also funds your account charge.
There was a plan to tax this. From April 2027, interest on cash held in stocks and shares ISAs was due to face a 22% charge, alongside a £12,000 cash ISA limit for under-65s. The Budget on 28 October 2026 cancelled those reforms, so interest on cash in a Dodl ISA stays tax-free. If you want a cash-like holding that is invested rather than sitting idle, Dodl’s range includes a sterling money market fund; money market funds in apps explains how they differ from cash.
How Dodl compares
| Monthly cost on | Dodl | Hargreaves Lansdown (shares and ETFs) |
|---|---|---|
| £5,000 | £1.00 | £1.46 |
| £20,000 | £2.50 | £5.83 |
| £50,000 | £6.25 | £12.50 (capped) |
| £100,000 | £12.50 | £12.50 (capped) |
HL figures use its 0.35% charge with the £12.50 monthly cap on shares and ETFs. Both exclude fund charges.
Against the zero-platform-fee apps such as InvestEngine and Trading 212, Dodl loses on pure cost: they charge no account fee on ETFs at all. What Dodl offers instead is a ready-made fund range, a Lifetime ISA and a pension in one place, and the backing of AJ Bell, a stock-market-listed platform that Dodl says is trusted by over 673,000 people.
Who Dodl suits, and who it does not
Dodl suits you if you want a low-cost Lifetime ISA, a simple ISA or pension holding one ready-made fund or a global tracker, and no decisions about dealing fees. It also works for someone who wants to move a cash ISA into investing without facing a large menu.
Look elsewhere if your ISA is above roughly £100,000 in ETFs (a capped fee wins), if your pot is small and spread across several accounts (the £1 minimums add up), if you want investment trusts or a wider fund choice, or if you need a Junior ISA or joint account. If you are moving money from another provider, read how to transfer an ISA between apps first: never withdraw and pay in again, or you lose the ISA wrapper.
Your investments are held by AJ Bell, which is regulated by the Financial Conduct Authority. If an investment firm fails, the Financial Services Compensation Scheme can cover eligible claims up to £85,000. That does not protect you from investments falling in value.
Frequently asked questions
Is Dodl any good? For low-cost, hands-off investing, yes. The 0.15% account charge with no dealing fees is cheap for funds and for accounts between about £8,000 and £100,000. The trade-offs are a short investment list, no Junior ISA, and a £1 monthly minimum per account.
How much does Dodl charge? 0.15% a year of the value of your investments in each account, collected monthly, with a minimum of £1 a month. Buying and selling is free. Fund ongoing charges, FX on US shares and stamp duty on UK shares are extra.
Is Dodl the same as AJ Bell? Dodl is AJ Bell’s app-based service, run by AJ Bell Dodl from Salford Quays. It uses a separate, smaller investment range and its own pricing. The main AJ Bell platform offers more investments and more account types, including Junior ISAs.
Does Dodl pay interest on cash? Yes, 3.80% AER variable on uninvested cash in the investment ISA and the Lifetime ISA. Cash in the Dodl pension and general investment account earns no interest.
Can I open a Lifetime ISA with Dodl? Yes, if you are 18 to 39. You can pay in up to £4,000 a year and receive the 25% government bonus. Existing Lifetime ISAs will continue after the planned First Time Buyer ISA arrives in April 2029.
What is the minimum to invest with Dodl? £25 a month by regular investment, or a £100 lump sum. Keep in mind the £1 monthly minimum charge, which is a high percentage of a very small balance.