Interactive Investor Review: £5.99 Beats 0.35% From £20,537
Interactive investor charges £5.99 a month up to £100,000. Where that beats a percentage fee, what trades and FX cost, and who should pay for Plus or Premium.
This interactive investor review comes down to one question: is your portfolio big enough for a flat monthly fee to beat a percentage? interactive investor (ii) charges £5.99 a month on its Core plan for everything up to £100,000, covering a Stocks and Shares ISA, a pension (SIPP) and a trading account together. That is £71.88 a year whether you hold £20,000 or £99,000. A platform charging 0.35% costs the same £71.88 at £20,537, and more above it.
The flip side is that ii charges £3.99 for most trades on Core, takes 0.75% on currency conversion, and is poor value for small pots. Every figure below comes from ii’s own charges page, checked on 17 November 2026.
interactive investor at a glance
| Core | Plus | Premium | |
|---|---|---|---|
| Monthly fee | £5.99 | £14.99 | £39.99 |
| Portfolio limit | Up to £100,000 | No limit | No limit |
| Accounts | ISA, SIPP, trading account | Plus Junior ISAs | Plus Junior ISAs and a Business Account |
| Free trades each month | None | 1 (£3.99 credit) | 10 (£29.90 credit) |
| Funds, per trade | £3.99 | £1.49 | Free |
| UK and US shares, ETFs, trusts | £3.99 | £3.99 | £2.99 |
| Other international shares | £9.99 | £7.99 | £5.99 |
| Regular investing | Free | Free | Free |
| Dividend reinvestment | £0.99 per holding | £0.99 per holding | Free |
| Foreign exchange | 0.75% | 0.75% to £50,000, 0.25% above | 0.25% |
| Free family accounts | None | Up to 5 | Unlimited |
| ii360 advanced platform | £20 a month extra | £20 a month extra | Included |
ii does not charge to transfer in or out. Phone dealing costs £49 a trade, on top of the online rate.
The three plans changed on 1 February 2026
If you read an older interactive investor review, the plan names will not match. ii replaced its Pension Builder, Investor and Super Investor plans with Core, Plus and Premium from 1 February 2026, as ii announced in December 2025. The changes that matter most:
- Core went up for single-account customers. An ISA under £50,000 used to cost £4.99 a month; it is now £5.99.
- Core got a lot cheaper for pension plus ISA customers. Someone holding a SIPP and an ISA under £75,000 paid £9.99 a month; between £75,000 and £100,000 it was £21.99. Both now pay £5.99.
- The Core limit doubled from £50,000 to £100,000.
- Premium was enlarged later in 2026. ii’s December 2025 announcement promised two free trades a month; its charges page now lists 10 free trades (a £29.90 monthly credit), ii360 and a Business Account at the same £39.99.
When a flat fee beats a percentage
A percentage fee grows with your money. ii’s fee does not, which is why the break-even point is the whole story. Here is where ii Core (£71.88 a year) overtakes the main percentage-fee platforms we have reviewed:
| Compared with | Their charge | ii Core is cheaper from |
|---|---|---|
| Hargreaves Lansdown, funds | 0.35% | £20,537 |
| Hargreaves Lansdown, shares and ETFs | 0.35%, capped at £150 a year | £20,537 |
| Vanguard UK | £48 a year under £32,000, then 0.15% | £47,920 |
| Dodl by AJ Bell | 0.15%, £1 a month minimum | £47,920 |
Two things make ii look better than this table suggests. First, the £5.99 covers your ISA and your SIPP together, so a couple of accounts do not add a second fee. Second, the Core price includes the pension: £2.50 of the monthly fee is the SIPP administration part, not an extra charge.
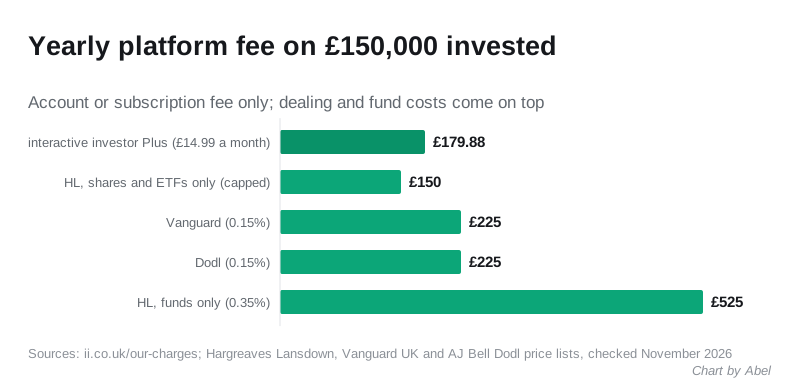
Above £100,000, ii moves you to Plus at £14.99 a month (£179.88 a year). Vanguard’s 0.15% catches up with that at £119,920, so between £100,000 and about £120,000 Vanguard is slightly cheaper. Beyond that ii pulls ahead, and Vanguard’s fee keeps rising to its £375 cap at £250,000 while ii’s stays at £179.88. The chart at the top shows the gap at £150,000.
Three worked examples
- £15,000 in an ISA, invested monthly in one fund. ii: £71.88. Vanguard: £48. Dodl: £22.50. Hargreaves Lansdown: £52.50. ii is the most expensive of the four. Small pots are where a flat fee hurts.
- £60,000 split between an ISA and a SIPP. ii: £71.88 for both. Vanguard: £90, because it adds accounts together for its 0.15%. Hargreaves Lansdown in funds: £210. ii wins clearly.
- £250,000 across an ISA and a SIPP. ii Plus: £179.88. Vanguard: £375. Hargreaves Lansdown in funds: 0.35% applies to each account separately, so £875. This is the sort of portfolio ii was built for.
Our investment platform fee calculator runs the same sums with your own balance and trading habits.
Trading costs: where the flat fee leaks
The monthly fee is only the start. On Core, every one-off buy or sell of a share, ETF or fund costs £3.99. Someone placing two trades a month adds £95.76 a year, which more than doubles their bill.
The way round it is regular investing, which is free on all three plans. If you put money in monthly and let ii buy the same funds or ETFs each time, you pay no dealing charge at all. Long-term index investors who set up a monthly plan and leave it alone get the full benefit of the flat fee.
Plus includes a £3.99 monthly credit, enough for one UK or US share trade, and cuts fund dealing to £1.49. The credit lasts 31 days and does not roll over.
Foreign exchange
Buying US shares means converting pounds to dollars, and ii’s Core charge is 0.75% each way. On a £10,000 purchase that is £75, and another 0.75% when you sell. Trading 212 charges 0.15% on the same conversion (see our Trading 212 review). If you mainly hold US shares directly, ii Core is expensive; buying a UK-listed fund or ETF that tracks the US market avoids the conversion altogether.
Is Premium worth £39.99 a month?
Premium costs £300 a year more than Plus. In return you get £25.91 a month more trading credit, cheaper share dealing (£2.99 against £3.99), free fund dealing, free dividend reinvestment, 0.25% FX on everything, and ii360, which costs £20 a month on the other plans.
Premium pays for itself if you would use most of the 10 free trades every month, or if you would otherwise pay for ii360. For someone who invests monthly and trades a handful of times a year, Plus or Core is the better buy.
Family accounts and Junior ISAs
This is ii’s least known strength. On Plus, up to five family members get their own ii accounts with no monthly fee, each holding up to £100,000. On Premium the number is unlimited and each can hold up to £250,000 with Premium dealing rates. Both plans include unlimited Junior ISAs. Core has no Junior ISA at all.
A household with £150,000 in a parent’s ISA and SIPP, a partner with £40,000 and two children’s Junior ISAs could hold everything for £179.88 a year on Plus. Compare that with the per-account charges in our best Junior ISA apps guide.
What ii does not offer
- No Lifetime ISA and no cash ISA. For those, see our best Lifetime ISA apps and best cash ISA apps.
- No commission-free dealing. Apps such as Trading 212 and InvestEngine charge nothing to trade and nothing (or very little) to hold, and are cheaper for anyone with less than about £20,000.
- No percentage fee at all, which cuts both ways, as the £15,000 example shows.
Is your money safe at ii?
ii is authorised by the Financial Conduct Authority, and your investments are held in a nominee company separate from ii’s own money. If ii failed, your holdings should be returned to you, and the Financial Services Compensation Scheme covers up to £85,000 if anything is missing. You can check ii’s entry on the FCA register. Our guide to whether your money is safe in an investing app explains how nominee accounts work.
Our verdict
interactive investor is one of the cheapest places in the UK to hold an ISA and a pension together once you have roughly £20,000 to £50,000 or more, and it gets better the bigger the portfolio and the more family members you bring. It suits buy-and-hold investors who use the free monthly investing plan.
It is the wrong choice if you have a few thousand pounds, trade often on the Core plan, or buy a lot of US shares directly. Start with our best stocks and shares ISA apps and best SIPP apps comparisons if you are still deciding.
Frequently asked questions
How much does interactive investor cost a month? £5.99 on Core for portfolios up to £100,000, £14.99 on Plus and £39.99 on Premium. The fee covers an ISA, a SIPP and a trading account together.
What happens when my ii portfolio goes over £100,000? ii moves you from Core to Plus at £14.99 a month. Accounts with Junior ISAs or family members added must also be on Plus or Premium.
Is interactive investor cheaper than Hargreaves Lansdown? From about £20,537 invested, yes, on the platform fee. HL’s 0.35% charge on funds costs £71.88 at that level and keeps rising, while ii Core stays at £71.88 up to £100,000.
Does interactive investor charge for regular investing? No. Regular investing is free on all three plans, which is the cheapest way to use ii. One-off trades cost £3.99 on Core.
Does interactive investor charge to transfer out? No. ii says it does not charge for transfers in or out, though your other provider may.
Does ii offer a Lifetime ISA? No. ii offers a Stocks and Shares ISA, SIPP, trading account and, on Plus and Premium, Junior ISAs.